Benefits Broker Versus Administrator: Key Differences
A benefits broker versus administrator comparison can feel like splitting hairs until you are the owner responsible for offering health benefits, answering employee questions, and keeping the program on budget. For a small business considering an HRA, the difference matters because these professionals often solve different parts of the same problem.
A broker can help you understand and select a benefits strategy. An administrator typically helps operate that strategy after it is in place. Some firms offer both services, while others specialize in one. Knowing who does what helps you avoid gaps, duplicate costs, and the assumption that someone else is handling an important task.
Benefits broker versus administrator: the basic difference
A benefits broker is usually an advisor and licensed insurance professional. Their role is centered on evaluating options, helping you compare approaches, and connecting you with benefits products or programs that fit your workforce and budget. If you have ever asked, “What can we afford to offer without locking ourselves into another unpredictable premium increase?” that is a broker-type question.
An administrator handles the day-to-day mechanics of a benefits arrangement. For an HRA, this can include enrollment, employee notices, substantiation of reimbursement requests, recordkeeping, privacy safeguards, and reporting tools. The administrator is generally the system and support structure that turns your chosen benefit into something employees can actually use.
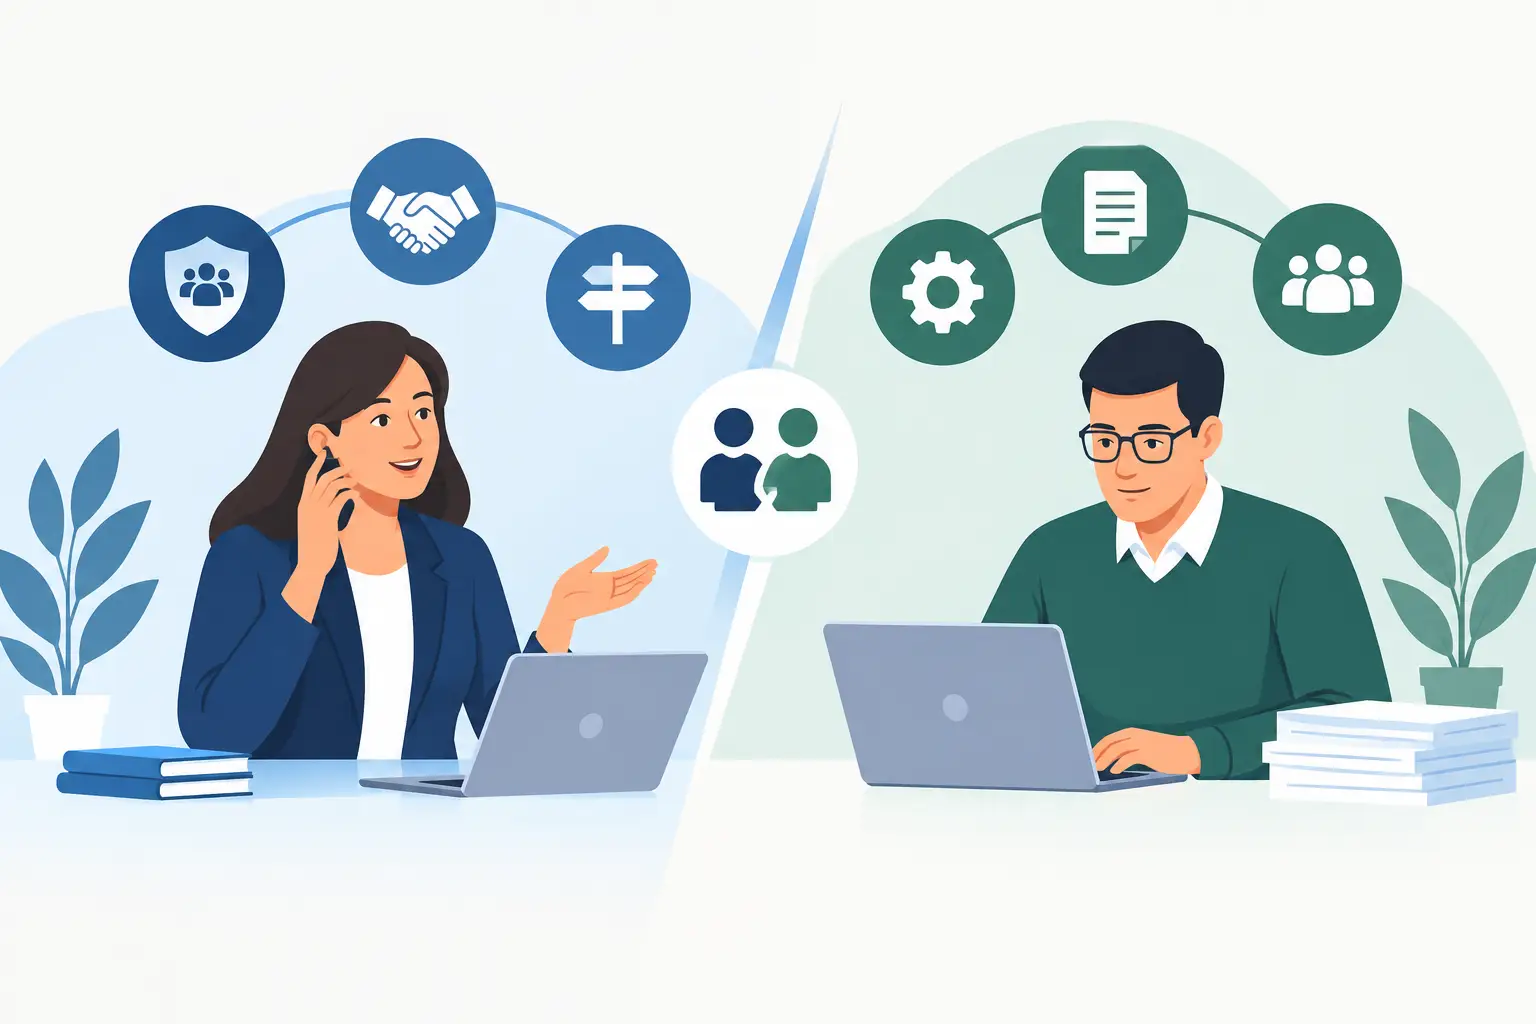
The distinction is simple: a broker helps you make the benefits decision; an administrator helps carry it out. In practice, there can be overlap, but small employers should ask clear questions about where each responsibility starts and ends.
What a benefits broker can do for a small employer
A good broker does more than send over insurance quotes. For a business with fewer than 50 employees, the right advisor should start with your goals: your monthly budget, the makeup of your team, whether employees are spread across different states, and how much administration you can realistically handle.
When an HRA may be a fit, a broker can help explain the available arrangement types and the conditions attached to them. For example, an Individual Coverage HRA, often called an ICHRA, can reimburse employees for individual health insurance premiums and eligible medical expenses when the rules are met. A Qualified Small Employer HRA, or QSEHRA, is designed for eligible smaller employers that do not offer a group health plan.
Those details affect eligibility, contribution design, employee classes, notices, and how employees obtain coverage. A broker can help you think through the trade-offs instead of treating “HRA” as one generic product.
A broker may also be the person who helps employees understand their individual coverage options, especially when an ICHRA requires them to have qualifying individual health coverage. That employee-facing guidance can be valuable, but do not assume it is included. Ask whether employees receive enrollment support, who provides it, and whether there is an added fee.
What an HRA administrator typically handles
An HRA is not a casual reimbursement policy where employees email receipts and the owner approves payments whenever there is time. It is a formal employer-sponsored health benefit with rules around plan documents, eligible expenses, substantiation, and privacy.
An HRA administrator provides the operational platform for these responsibilities. Depending on the provider and arrangement, that may include preparing plan documents, delivering employee notices, managing enrollment, reviewing substantiation, tracking allowances, and creating reimbursement reports for the employer.
This support can remove a major burden from a small office. You do not want a manager or bookkeeper trying to decide whether a medical expense qualifies, storing sensitive health information in a shared inbox, or manually tracking remaining balances on a spreadsheet.
The administrator can also give employees a clear place to submit requests and check their available benefit. That experience matters. Even a generous monthly contribution will not feel helpful if employees cannot understand how to access it.
Still, administration is not the same as strategic advice. An administrator may explain how its platform works, but it may not evaluate every health benefits option for your business or provide insurance guidance. Some administrators also do not offer individual plan shopping or employee enrollment help. Those are questions to settle before you sign up.
Do you need a broker, an administrator, or both?
For many small employers, the answer is both – but not always as two separate vendors. You may work with a broker who recommends an HRA and introduces an administration platform. Or you may begin with an HRA administrator, then bring in a broker for insurance-related guidance and employee support.
What matters is not the label on the provider. What matters is whether the work is covered.
If you already know the HRA type you want, understand the contribution limits and eligibility rules that apply, and have a trusted advisor for tax and legal questions, your immediate need may be an administrator. If you are still comparing group coverage, an HRA, or a different approach, start with advisory help. Choosing a platform before deciding on the strategy can put the cart before the horse.
For a very small team, one provider that coordinates the broker and administrative sides may feel easier. For a growing company with more complex employee classes or multiple locations, separate specialists may give you more flexibility. There is no universal right setup. The right setup is the one that matches your needs without leaving you to coordinate every detail alone.
Questions to ask before choosing support
Before committing to a broker, administrator, or combined solution, ask who owns each responsibility. Clear answers are more useful than a long feature list.
Ask these questions during your conversations:
- Who helps us determine whether an HRA is appropriate for our company?
- Which HRA types do you support, and what are the limits or requirements we should understand?
- Who prepares required plan documents and employee notices?
- Who reviews employee reimbursement requests and protects personal health information?
- Will employees receive help understanding or enrolling in individual coverage when needed?
- What will we need to do each month, and what will our bookkeeper need at tax time?
- Are there setup, monthly, per-employee, broker, or renewal fees beyond the quoted price?
Pay attention to vague answers. If a provider says, “We take care of everything,” ask for the workflow in plain English. Find out what happens when a new employee joins, an employee leaves, someone asks a coverage question, or a reimbursement request is denied. Those ordinary moments reveal whether the support model works for a small business.
Watch for the handoff problem
The most common frustration is not that a broker or administrator failed at their core job. It is that the handoff between them was unclear.
A broker may assume the administrator will explain employee eligibility. The administrator may assume the broker will help employees shop for coverage. The employer may assume the payroll provider is handling reimbursements. Then an employee is confused, a deadline is missed, or the owner spends an afternoon chasing answers.
Prevent this by asking for a simple implementation map before launch. It should identify who communicates with employees, who collects enrollment information, who handles reimbursement questions, how reimbursements move through payroll or accounts payable, and who is your main contact when something goes wrong.
You should also involve your accountant or tax professional where appropriate. A broker and administrator can provide valuable benefits guidance and operational support, but they are not automatically providing legal or tax advice for your specific business.
Focus on the outcome, not the job title
Traditional group insurance often pushes small employers toward a familiar but expensive path: pick a plan, accept annual renewal changes, and hope the budget holds. Reimbursement-based benefits can offer another way to provide meaningful support with a defined employer contribution.
But flexibility only helps when the program is designed and administered carefully. The goal is not to collect the most vendors or buy the flashiest software. The goal is to give employees a benefit they can understand while giving your business a predictable, manageable process.
Start by getting clear on your budget, your employees’ needs, and the level of help you want. From there, the broker, administrator, or coordinated team should make the next steps easier – not turn health benefits into another full-time job.