How to Classify ICHRA Employees Correctly
A two-person office and a 25-person field service company may both want predictable health benefit costs. But they should not automatically offer the same ICHRA allowance to every employee. The ability to classify ICHRA employees gives small employers a practical way to build benefits around real job structures, as long as the classifications follow the rules.
An Individual Coverage HRA, or ICHRA, lets an employer reimburse employees for eligible individual health insurance premiums and qualified medical expenses. It can replace a traditional group plan or sit alongside one for different employee groups. The flexibility is useful, but it is not a blank check to create categories based on who is likely to cost more.
The goal is simple: create classes that make business sense, treat similarly situated employees consistently, and are easy to explain when someone asks why their allowance differs from a coworker’s.
Why employee classification matters with an ICHRA
Traditional group health insurance often asks a small business to accept one plan design, one carrier network, and premium increases that can be difficult to budget for. An ICHRA changes the funding approach. You decide the monthly contribution amount, while eligible employees choose individual coverage that fits their needs.
Classification is what makes that approach workable for a business with different types of employees. A growing company may have full-time office staff, part-time support, seasonal workers, and employees working in multiple states. Treating every group exactly the same may not match the company’s budget or hiring needs.
At the same time, a poorly designed classification strategy can create compliance concerns, employee frustration, and an arrangement that is hard to administer. Before choosing allowance amounts, decide which employee groups are genuinely distinct and whether you can apply the rules consistently.
The employee classes you can use
ICHRA rules allow employers to use specific employee classes. You cannot simply invent a category such as “employees with expensive medical needs” or “people who did not enroll last year.” Classifications must be based on permitted employment-related factors.
Common permitted classes include:
- Full-time employees and part-time employees
- Salaried employees and non-salaried employees
- Temporary employees and seasonal employees
- Employees working in different states or insurance rating areas
- Employees covered by a collective bargaining agreement
- Employees in a waiting period
- Employees hired on or after a specified date
- Nonresident aliens with no U.S.-based income
There are also rules permitting certain combinations of these classes. For example, a business might distinguish full-time salaried employees from part-time hourly employees if that reflects how the company actually operates.
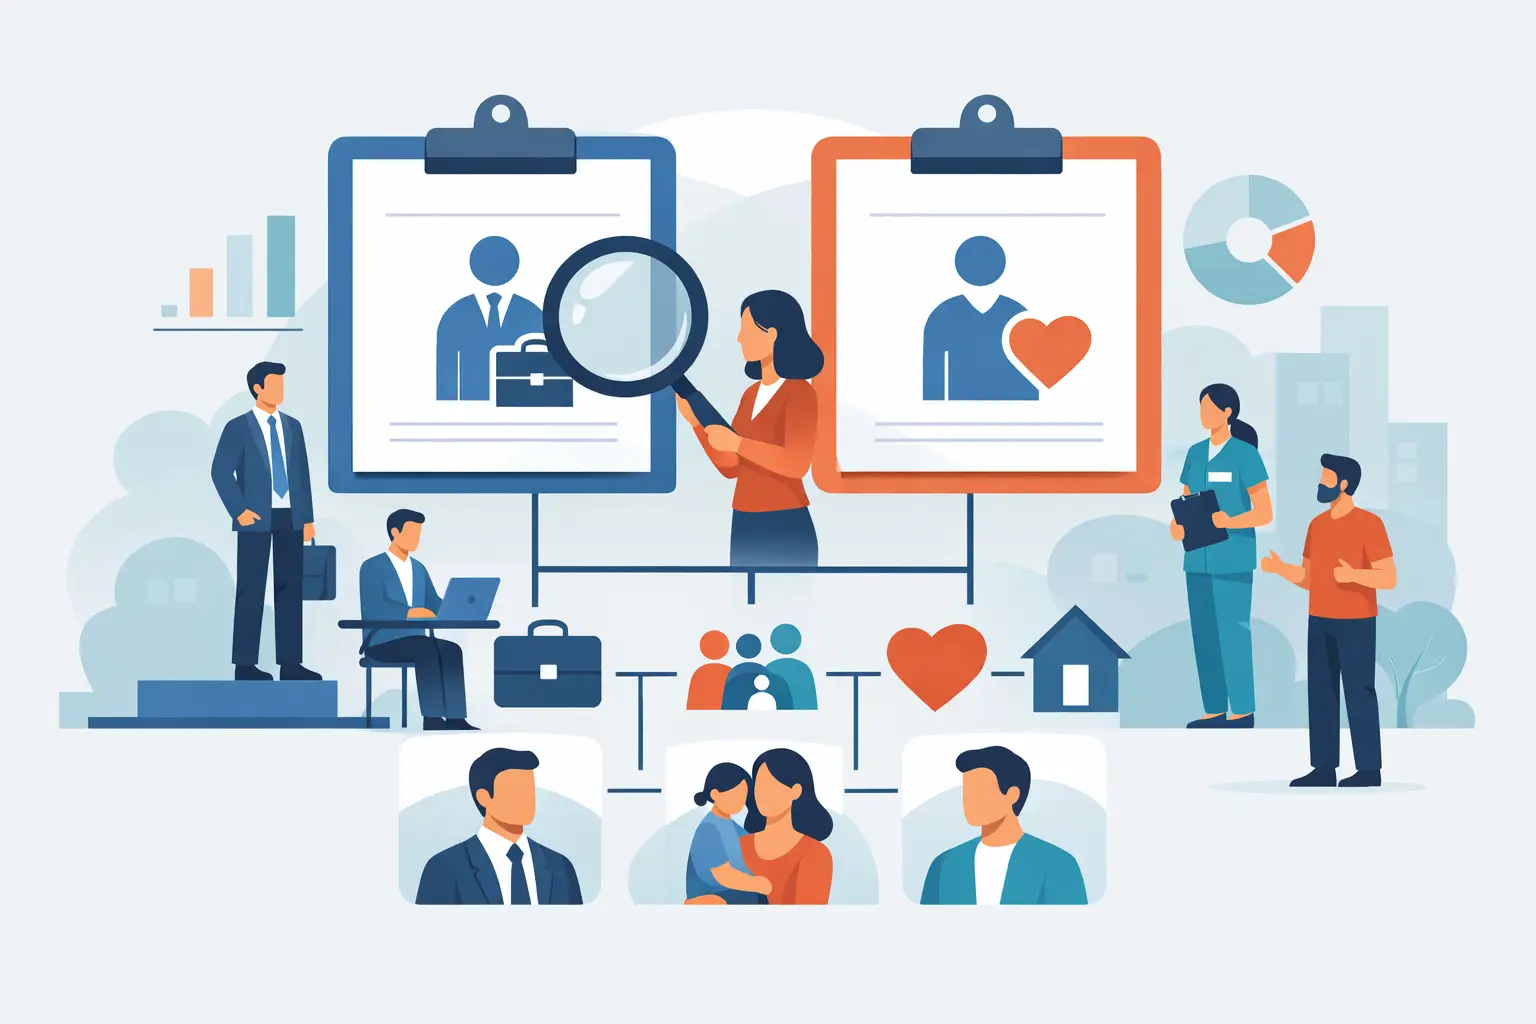
For many small employers, the most useful starting point is much simpler: full-time versus part-time, employees in different locations, or a new-hire group. More categories are not automatically better. Each additional class creates another set of decisions, communications, and administrative steps.
A practical example
Consider a 16-person marketing agency. It has 10 full-time employees, four part-time employees, and two seasonal interns. The agency wants to offer a meaningful health benefit to its full-time team but cannot afford to provide the same amount to every worker.
It may choose to offer an ICHRA to full-time employees, provide a smaller allowance to part-time employees, and exclude seasonal interns if the arrangement is structured properly. That is far easier to support than deciding allowances employee by employee based on tenure, personal health needs, or salary negotiations.
The business rationale should be clear enough to explain in one or two plain-English sentences. If it is difficult to explain, it may be too complicated.
How to classify ICHRA employees without creating problems
Start with your existing workforce structure, not with the allowance amount you hope to spend. Look at job status, hours, pay structure, work location, and employee start dates. These are the kinds of distinctions the rules are designed to accommodate.
Next, identify the business reason for each class. A multi-state employer may need separate classes because individual-market options and premium costs vary by location. A contractor-heavy business may distinguish its year-round full-time team from a seasonal workforce. A professional services firm may want a different approach for newly hired employees while maintaining an existing group plan for longer-tenured staff.
Then apply the arrangement consistently within each class. In general, employees in the same class should receive the same terms. Employers may vary the allowance based on age and family size within permitted limits, which can help make benefits more equitable for employees with dependents. The variation should follow a consistent formula, not a manager’s preference.
Finally, document your choices before you announce the benefit. Write down each class, who falls into it, the allowance for that class, when eligibility begins, and how employees will be informed. Clear documentation helps your administrator set up the plan correctly and gives you a dependable answer when employees have questions.
Watch for the group plan and ICHRA split
One of the most common ICHRA design mistakes happens when an employer wants to keep a traditional group health plan for one segment of the workforce while offering an ICHRA to another. This can be allowed, but the employee classes must be valid and, in some situations, minimum class-size rules apply.
For example, an employer generally cannot offer the group plan to a handful of employees it expects to have higher health costs and push everyone else into the ICHRA. The rules are intended to prevent employers from using classifications to separate people based on health status or expected claims.
Minimum class-size requirements can apply when an employer offers a traditional group plan to one class and an ICHRA to another. The threshold depends on the employer’s size and the class involved. Small businesses with fewer than 100 employees may need at least 10 employees in a class subject to the rule. There are exceptions and details, so this is a good point to review with an experienced benefits professional before finalizing the design.
Consider affordability if you are an applicable large employer
Most HRA Geeks readers have fewer than 50 full-time equivalent employees, so the Affordable Care Act employer mandate may not apply. Still, growing businesses should pay attention to this issue.
If you are an applicable large employer, generally one with 50 or more full-time equivalent employees, an ICHRA offered to full-time employees may need to meet affordability requirements to avoid potential penalties. Affordability calculations can vary by employee location, age, and the lowest-cost available individual coverage option.
That does not mean ICHRA is off the table. It means the allowance amount and employee classes need more careful planning. A business nearing the 50-employee threshold should not wait until open enrollment to sort this out.
Communicate the classification in plain English
Employees do not need a lecture on federal benefits regulations. They do need to understand whether they are eligible, how much reimbursement is available, what coverage they need to maintain, and when to take action.
Keep the explanation direct. For example: “Full-time employees scheduled to work 30 or more hours per week are eligible for a monthly ICHRA allowance of $450. Part-time employees are eligible for $150 per month.” If location affects the benefit, explain that as a practical response to different local individual-market costs.
Remember that employees generally need individual health coverage or Medicare to participate in an ICHRA and receive reimbursements. They will also need proper notice before the plan year begins, giving them time to evaluate coverage choices. Your benefits administrator can handle much of the process, but the employer should still understand the message being delivered.
A simpler way to make the decision
The right classification structure is usually the one that matches your actual workforce and can hold up as the company grows. Do not build a complicated system just because the rules permit it. A clean, defensible approach is often better for your budget, your employees, and your future administrative workload.
If you are unsure where to draw the lines, begin with an employee census showing job status, hours, location, and anticipated hires. From there, you can evaluate whether an ICHRA design gives your team meaningful support without putting your business back into the cost unpredictability you were trying to escape. Clarity at the design stage makes every later benefits conversation easier.