How to Choose HRA Plan Type for Your Small Business
A group health renewal that jumps 15% can make a benefit feel less like a perk and more like a budgeting emergency. If that sounds familiar, you may be looking at reimbursement-based benefits for the first time. The question is not simply whether an HRA can work. It is how to choose HRA plan type that fits your budget, your employees, and the way your business operates.
For many small employers, the practical choice comes down to a QSEHRA or an ICHRA. A group coverage HRA may also make sense if you want to keep a traditional group plan. Each option handles reimbursements differently, and the right answer depends on a few business facts that are easy to identify before you get buried in benefits terminology.
Start with the problem you are trying to solve
An HRA is an employer-funded arrangement that reimburses employees for eligible health care costs. Depending on the plan type, that can include individual health insurance premiums, out-of-pocket medical expenses, or both. You decide the monthly allowance. Employees submit eligible expenses for reimbursement, and unused funds generally stay with the business rather than becoming a cash account employees take with them.
That budget control is a major reason small businesses consider HRAs. But do not choose based on the monthly allowance alone. Ask what you need the benefit to accomplish.
Are you replacing a group plan that no longer fits? Are you offering health benefits for the first time? Do most employees already have individual coverage, or do they rely on a spouse’s plan? Do you have a mix of full-time staff, part-time staff, seasonal workers, or employees in multiple states?
Your answers shape the plan type. A simple arrangement can be a better fit than a highly flexible one if your team and goals are straightforward. On the other hand, a growing business may need more design options than a basic arrangement allows.
Choose HRA plan type: QSEHRA or ICHRA?
QSEHRA: Often the simpler option for very small employers
A Qualified Small Employer HRA, usually called a QSEHRA, is designed for employers with fewer than 50 full-time equivalent employees. To offer one, the employer cannot offer a group health plan to any employee.
With a QSEHRA, you set an annual reimbursement allowance within federal limits. Eligible employees can be reimbursed for qualified medical expenses and, when they have minimum essential coverage, individual health insurance premiums. The arrangement is generally offered on the same terms to eligible employees, although reimbursement amounts can vary for permitted reasons such as family size and age.
For a small company with a relatively consistent team, that structure can be a benefit rather than a limitation. It gives you a defined budget, a clear employee benefit, and fewer design decisions to manage. A five-person consulting firm that has never offered benefits, for example, may find a QSEHRA easier to explain and administer than a more customizable arrangement.
The trade-off is flexibility. QSEHRA contribution limits apply, and the rules do not allow you to create as many employee classes or contribution strategies as an ICHRA. It is also not an option if you want to continue offering a group health plan.
ICHRA: More flexibility for changing teams
An Individual Coverage HRA, or ICHRA, can be offered by employers of any size. It reimburses employees for individual health insurance premiums and eligible medical expenses, but employees must be enrolled in qualifying individual health coverage or Medicare to participate.
Unlike a QSEHRA, an ICHRA has no federal maximum contribution amount. You still set your own budget, of course, but you have more room to tailor allowances around your workforce. Employers may use permitted employee classes, such as full-time versus part-time employees, workers in different geographic locations, salaried versus hourly staff, or new hires. Specific class rules and minimum class sizes can apply, especially when an employer offers a group plan to another class.
That makes ICHRA useful for businesses with more variation. Consider a 30-person service company with employees in three states, a mix of office staff and field workers, and a hiring plan for next year. The employer may want to offer different benefit approaches to clearly defined groups while keeping contributions predictable. ICHRA can provide that flexibility when it is designed carefully.
More flexibility also means more decisions. Employee classes must be legitimate and applied consistently. Employees need clear notice and enough time to evaluate individual coverage. Applicable large employers also have affordability rules to consider under the Affordable Care Act. If your team is nearing 50 full-time equivalent employees, get guidance before assuming any ICHRA design will meet your obligations.
Group coverage HRA: A supplement, not a replacement
A group coverage HRA is generally paired with a traditional group health plan. It can help employees pay eligible out-of-pocket costs, such as deductibles, copays, and other qualified expenses not fully covered by the group plan.
This option may fit a business that wants to retain group coverage but make the plan more valuable without moving to a richer, more expensive policy. It does not solve the same problem as QSEHRA or ICHRA. If your goal is to move away from group insurance and help employees buy their own coverage, a group coverage HRA is not usually the starting point.
Compare the employee experience, not just the employer cost
A fixed monthly allowance may look similar on paper across HRA types, but the employee experience can be very different. With an ICHRA, employees must obtain and maintain qualifying individual coverage. That works well for employees who value plan choice or already purchase coverage on their own. It can feel unfamiliar to employees who have only used employer-sponsored group plans.
With a QSEHRA, employees may also use reimbursements for qualified out-of-pocket expenses, subject to the plan rules. That can be helpful for employees covered through a spouse, Medicare, or another arrangement, although the tax treatment and eligibility details can vary by circumstance.
Before choosing, look at your employee census. You do not need to ask employees for private medical information. You do need a practical sense of where coverage comes from today, where employees live, what family sizes look like, and whether a meaningful share of your team needs help finding individual coverage. A plan that is technically available but poorly understood will not feel like a strong benefit.
Build the budget from a monthly number you can keep
The appeal of an HRA is not that it makes health care inexpensive. It is that it lets you set a contribution you can sustain. Start with a monthly allowance per employee or per employee family category, then test that number against annual cash flow, expected hiring, and administrative costs.
Avoid setting an allowance based only on what you can afford this month. Consider whether you can maintain it through a slower season, a new hire, or a year when revenue is flat. A modest, dependable benefit is usually better for morale than a generous allowance that has to be reduced after six months.
Also separate the reimbursement budget from the administration budget. HRAs require plan documents, expense substantiation, privacy-conscious handling of health information, and employee notices. Most small businesses use an HRA administrator for these tasks. That adds a cost, but it can reduce the chance that an owner or office manager is left sorting through receipts and compliance questions.
Watch for the decisions that create compliance problems
HRAs are employer health plans, not informal reimbursements. You cannot simply promise to pay employees back for insurance or medical bills through payroll and expect the same tax treatment. A properly structured HRA needs formal documents and a process for verifying eligible expenses.
The common trouble spots are offering the wrong combination of benefits, using employee classes improperly, missing required notices, and failing to verify coverage when a plan requires it. For QSEHRA and ICHRA, employees may also need information about how the benefit interacts with premium tax credits from the Health Insurance Marketplace.
This is where plain-English advice matters. A benefits professional or administrator can help you review your employee count, existing coverage, contribution goals, and implementation timeline before you announce anything. Your accountant can also help you understand the tax and payroll implications for your business.
A practical way to make the decision
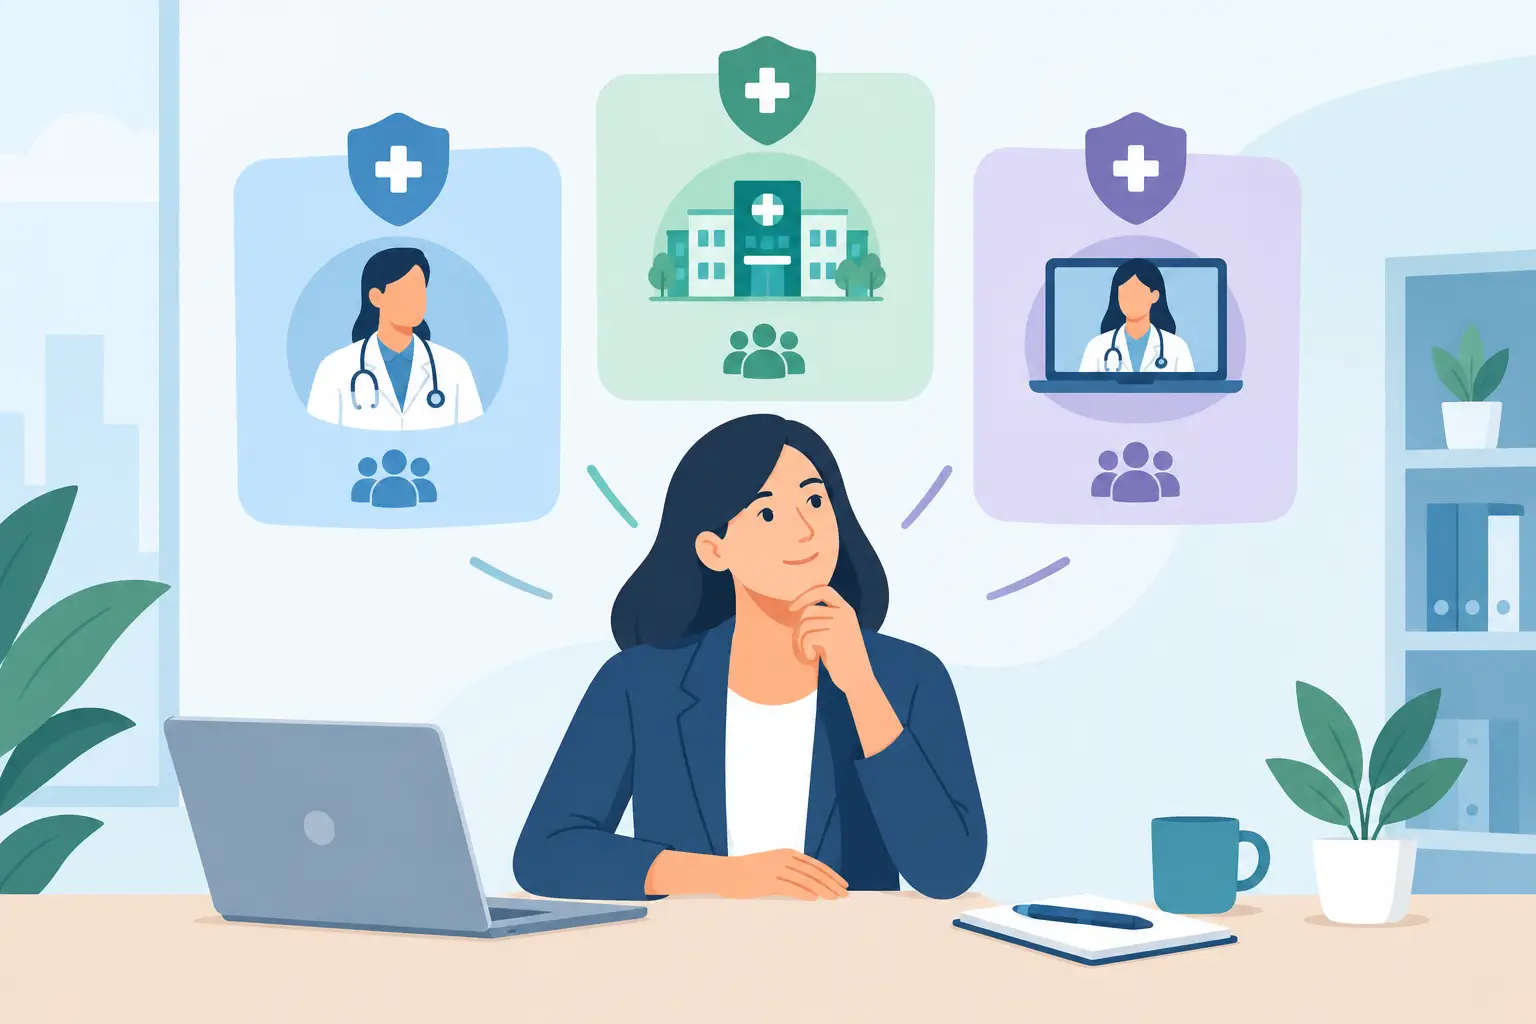
If you have fewer than 50 full-time equivalent employees, do not offer group coverage, and want a straightforward defined contribution benefit, QSEHRA deserves a close look. If you need broader flexibility, want to use permitted employee classes, have a geographically spread-out team, or may grow beyond the small-employer threshold, ICHRA may be the stronger fit. If you are keeping group insurance and want to help with out-of-pocket costs, a group coverage HRA may be worth discussing.
The best next step is to put your real numbers on one page: employee count, current benefits, monthly budget, expected hiring, and the employee groups you want to cover. From there, the right HRA plan type becomes less of an insurance puzzle and more of a business decision you can explain with confidence.